Startup Sale! 80% Off
About this episode
 Spotify
 Apple Podcasts
Ramya Possett and Rachel Lee founded BlueFoot to make tracking the competition easy for massive companies. And they think that what they’ve created is so powerful, it demands a premium price tag. One that takes the investors completely by surprise.
Today's investors are Jillian Manus, Charles Hudson, Phil Nadel, Michael Hyatt and Sarah Downey.
The Panel
Forefront Venture Fund
“When I'm investing, I'm looking at it strictly as a return on investment.”
“Necessity is the mother of all invention. You've invented this because you want to solve a problem that you had. That's exactly where great businesses all start.”
“Is this risky? Hell yeah. But I'm willing to take a risk on somebody who will jump in a car in LA and go for it.”
Sarah: Hello.
Jillian: Hello. You’re blue footed boobies. All right. Okay.
Michael: What is it called?
Jillian: Blue footed booby. You find them in Galapagos.
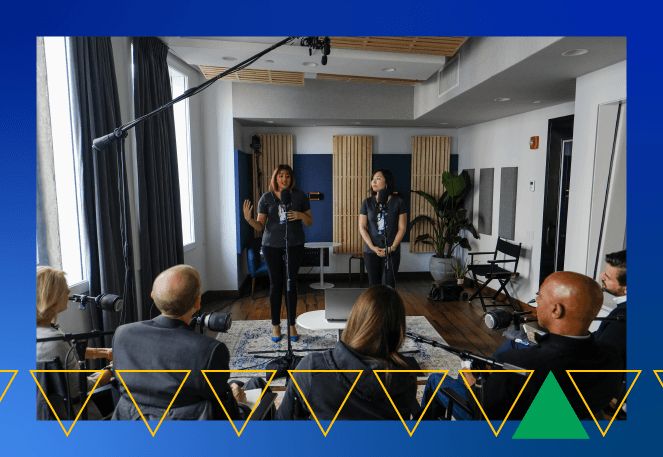
That’s one way to make an entrance. Today’s founders walk in wearing matching blue heels along with t-shirts with a blue footed booby bird on them. And all this immediately grabs the investors’ attention, which is good because they’re here to pitch their startup fittingly named BlueFoot.
Today’s founders are Ramya Posset and Rachel Lee who say that BlueFoot is a powerful research tool that allows big companies to keep tabs on their competition, which could be huge. Because if you’re a tech company like Apple, for example, staying 10 steps ahead of Google is a billion-dollar game.
Let’s see if the investors wanna play. From Gimlet, this is the Pitch. I’m Josh Muccio. Today’s investors are:
Sarah: Sarah Downey.
Sarah used to run her own company, now she’s a partner at Accomplice and an angel investor making bets on early-stage startups.
Phil: Phil Nadel.
As a serial entrepreneur, Phil built companies that sold for hundreds of millions of dollars.
Now he manages Forefront Venture Partners, one of the largest syndicates on AngelList.
Jillian: Jillian Manus.
Jillian is a partner at Structure Capital, where they’ve invested 98 million so far in high profile startups like Uber.
Michael: Michael Hyatt.
Michael built and sold two software companies for over $500 million, and now he invests for himself.
Charles: Charles Hudson.
Charles started Precursor Ventures, where he has invested 20 million in over a hundred startups to date.
All right, on with The Pitch.
Rachel: My name’s Rachel Lee.
Ramya: Hi, I’m Ramya Possett, and we are the co-founders and CTOs of BlueFoot. BlueFoot was born from a problem that Rachel and I faced throughout our careers in legal and in tech, and most recently, as in-house counsel at HP. Rachel managed the portfolio for big data and I managed the portfolio for cybersecurity. For both of these lines of business, we had to keep track of different competition, and it can be very time consuming and complex. Companies can spend over a million dollars a quarter to get hundreds of reports, Excel spreadsheets, and all this other information, and then internally, they have to take the 10,000 hours of blood, sweat, and tears to try and make sense of all of it.
Rachel: That’s why we started BlueFoot. BlueFoot marries Wall Street financial data with technology, products and patents. So Ramya could BlueFoot the competitor that she cares about in cybersecurity. And I could BlueFoot my competitors that I want to monitor in the data space. With a click of a button, you could see all of these data on one single dashboard with complete and real-time competitor data.
Ramya: And this software is actually already built. We’re launching with a household name in about three weeks, and we’re here raising $3 million to roll out to ten more clients. Thank you.
Michael: So can you be a little more specific here? Because I think if I had a Bloomberg terminal, I can already do this. Right?
Ramya: So with a Bloomberg terminal, you can get financial data, but you’re not necessarily gonna get data about patents or the products. And we actually have a demo, if you’d like to see.
Michael: Please. Yes.
Ramya: We are, we are selling to -
Jillian: So this is all public data, right? That you’re sort of aggregating? Correct. And then, okay, let, let’s see the product.
Ramya: Let’s see the product. Yeah. So, can everybody see the screen?
Jillian: Yes.
Ramya: Okay, perfect. So this is one of the main pages of BlueFoot. It’s called the Company Intel page. And you can choose the companies that you follow here. So…
Ramya and Rachel pull up the BlueFoot web product on a laptop to show the investors. The demo page shows companies like Alphabet and Lenovo, and then it has columns with their most recent financial, product, patent and M&A data. And there’s a trend line for each showing how that activity has changed over the past three years. It’s all meant to help companies see what technologies the competition is betting on years before that tech even sees the light of day.
Sarah: Can you get a little bit more into the data sources that you’re aggregating for maybe each of these categories?
Rachel: So we are partnering with two main data providers. One is the one of the Wall Street data providers. We’re getting their data and they’re mostly revenue data. And we have, we’re working with another data provider, provides patent data, so we have revenue share model with them. So we’re bringing those two data, right.
Sarah: What does the rev share look like with them?
Ramya: That’s actually confidential, but it’s, I mean, we’re lawyers and we’re pretty happy with how we negotiated.
Michael: So then, talk to us about the revenue. What, what do you think the next 12 months are gonna look like for your business?
Ramya: Sure. So as we said, we’re launching with a household name in about three weeks, and we hope to get ten more clients in the next year. And we think that this is a $500,000 value for a department-wide license. So -
Michael: So this is a big enterprise software license?
Ramya: Exactly. And I mean, we’re gonna give significant discounts to early adopters, but that, that kind of gives you -
Michael: So 500,000 per customer?
Rachel: Per department.
Ramya: Per department.
Michael: Per department, per year.
Ramya: Yes.
Michael: So a typical - your ten clients that you think you’re gonna sign, how much revenue does that represent?
Ramya: So the discounts that we give per client is based on negotiation and again, under NDA, but I mean, we do plan for early adopters to give significant discounts, but we, we do think that it’s gonna be revenue that’s, that’s over a million a year.
Jillian: So you don’t have to tell us, okay, who that next customer is. But you do have to provide us some sort of understanding of the unit economics here.
Ramya: Sure.
Jillian: Because for me, 500,000 per department. That’s a very big lift. Okay. For any enterprise, for anyone, and - so can you walk us through a little bit about, as you’re saying, the discount and how you really think that you’re gonna be able to sell more than one department?
Rachel: So our, um, first go-to-market strategy is of course the patent department. So we’re going to do direct sales, the ten customers that we’re talking about for next year, we’ll be leveraging our personal networks in these enterprise, uh, companies. And then we’re, we’re thinking around 50 to even 60% discount, um, for these early adopters next year.
Jillian: So when you’re talking about 50 to 60% discount, 50% discount off of 500,000, which is what you think that you can get for this?
Ramya: Yes. And you know, we’ve, um, we’ve had conversations. So when we started this process, we started with our market fit validation process and we’ve also started validating price point as well.
Michael: Do you have anybody willing to pay you half a million bucks right now?
Rachel: We have, uh, people willing to pay over 200 right now. So, you know, cause I, I mean, for early adopters, adopting new system is we know that it’s gonna be a hard sell at $500,000, right?
Michael: Oh, yeah.
Sarah: Are you the sales - like, can you, can you explain - is there the broader team besides the two of you and who’s actually selling? Because it does sound like to build an enterprise sales model, you need to have a machine, and that’s a really complicated in depth thing. So I mean, so much of this is dependent on those sales. So can you talk more about that?
Rachel: So right now we are the two salespeople. Right. And we have our, our, I mean, just team structure wise, right, we have our development team from Ukraine, Eastern Europe.
Jillian: They’re great.
Rachel: Yeah, they’re great. They’re ten people working for us.
Phil: And what about the sales role? Do you have background experience in sales?
Jillian: Are you bringing on a salesperson with this round?
Ramya: Uh, yes, we are, we’re bringing on a salesperson. So our, as Rachel mentioned, our go-to market strategy starts with IP departments, but where we also see major need from our market fit validation is M&A teams. And it’s surprising how much of this can be kind of word of mouth. Like, I went to business school with someone who’s got this, or I, you know, I saw this news article or whatever. And more and more C-suites wanna be data driven.
Jillian: Tell me about the competitive landscape. Is there anybody doing this? Because I think there is one.
Phil: I’ve seen a number of companies providing very similar services, but aggregating a lot more data sources and normalizing all the data into a - what seems to be a much more robust platform.
Rachel: So we have a number, I mean, obviously number of competitors in the kind of financial data analytics side and we have a, a lot of competitors in patent analytics side. What we - based on our research, there’s no one company or no one platform that brings them together. So I think that’s our differentiator. Bringing technology data into financial data. So marrying the Wall Street data with technology.
Jillian: But couldn’t that be done by anybody who’s already - has half of this built or 80% of it built, so they can just add that on to it?
Rachel: So, um, patent data to like - for instance, mapping patent data to industry and so that it makes sense how that maps to revenue is extremely hard process. We have built machine learning algorithm that keeps getting better. So what we did, we push a lot of good quality training data that enables, after a machine reads a patent, and understand how it’s mapped to these industries is the key critical part of it. And to build that, it’s, um, it’s gonna take time, right? Um, so that’s the portion that will be difficult for other competitors to catch up with.
Ramya: A lot of the major companies that you know, actually just have manpower doing it, right. We, we talked to somebody at a major tech company a couple weeks ago, and they were saying it takes them three weeks of one full-time person to map one company’s patents for one year into industries, and then next year they have to redo the same thing. Three full weeks of one person full-time. And if they, if there was something out there doing this, I mean, these are companies that spend resources on competitive intelligence information.
According to Ramya and Rachel, BlueFoot’s secret sauce is the way it uses the sources to compare companies, and that it’s done with a little good old-fashioned ML, AKA machine learning. And the investors, they seem to get it, even if they’re skeptical about how much Ramya and Rachel are charging for it. But when we come back, they’ll hear a different number, one that sends shockwaves through the room.
Michael: That’s a terrifically high number for a company with - like, with respect this, this pitch is either completely useless or it’s not.
Welcome back to the show. The co-founders of BlueFoot have just made the case that their company is unique and solves a big problem, but they’re about to drop a bomb on the investors.
Michael: How much money are you raising and at what valuation?
Jillian: 3 million.
Ramya: 3 million. Yes, at a 30 million valuation.
Jillian: Sorry?
Ramya: A 30 million valuation.
Michael: And you have zero revenues today?
Ramya: Yes. By the time we close, we hope to have, uh, a, a potentially multi-year, um, contract with the company that we’re talking about.
Michael: Worth how much?
Ramya: We’re still in the negotiation process and we don’t want to -
Michael: Okay. Look, you’re not - okay. You come in here, you want 3 million on 30. That’s a terrifically high number for a company with - like, with respect, this pitch is either completely useless or it’s not. I mean, like, if you’re not gonna tell us anything, then what do you want me to do? You’re asking for an exorbitant number. If I’m gonna take you seriously, you’ve gotta act, you don’t have to give me names, but you’re gonna have to be more specific or I’m just like, I don’t know why I’m here.
Ramya: Sure. So for that, um, for a one year - a one or two, a two year contract, it would be around probably one and a half million.
Phil: So you, you’re raising 3 million. How much of that is committed? Do you have a lead investor? How is the $30 million valuation determined?
Ramya: So we are just starting the fundraising process. We wanted to wait until we were close to launching our beta with this household name. And that’s, this is actually, uh -
Jillian: First one.
Ramya: One of our early -
Phil: So the two of you got together -
Michael: How did you come up with the 30? Like -
Phil: The two of you got together and said, okay, we’re gonna raise 3 million. What valuation are we gonna put on it? Uh, how about 30 million? How’d you come up with that?
Ramya: Oh, it wasn’t quite that.
Phil: Oh, I’m asking. I’m not, I’m not judging. I’m asking how you came up with 30 million.
Ramya: Yeah, so, um, we actually talked to, you know, we’ve been getting a lot of feedback and mentoring from VCs and other serial entrepreneurs that we knew, and they basically said, take the amount that you’re looking for, and then, you know, 10, that’s 10% or 15% of how much you wanna raise. Right? Like, that’s normally if you have, if you’re looking to raise a seed, just kind of go with that calculation. And we also -
Michael: So this is not an A round, this is your seed round at 30 million pre.
Ramya: Mm-hmm. We do recognize to some extent it is a little pie in the sky, but if you don’t, you know, we are willing to negotiate on things like valuation. And secondly, there are some things that we take into account, right? For SaaS enterprise companies we have looked at kind of the, the multiples for valuation. And while we don’t have revenue now, um, we think that if we can get these, you know, these ten licenses by the end of the, you know, that 18 month run rate of the 3 million, we will be –
Michael: Whoa. Okay. So stop. Okay, so stop, stop, stop. So you would like us to pay for something that could come in 18 months from now?
Ramya: I think you pay for the potential of being -
Michael: Now think, think - what you should be doing is de-risking the investment. You’re first-time entrepreneurs. I assume either of you haven’t sold companies for hundreds of millions.
Ramya: No.
Michael: Okay. Uh, this is your first, this is this first time doing this?
Ramya: This is our first venture, yes.
Michael: Okay, so let’s talk about that. So, if you were a multi exit entrepreneur and you were a name brand and stuff like that, I think all of us would say, oh, you’re going back in again. We would probably give you money no matter what the idea is because we’re betting on the person. But that’s not the situation here.
Let me give you just some un - you didn’t ask for this advice, but let me just give it to you. If I were you, I took a look at this, this product. With respect, it’s meh. It’s okay. I mean, it’s missing a lot. I mean, you’re aggregating a lot of public data. Maybe you got some machine learning, but so does everybody, and you’re not inventing that. You’re bringing it together. It’s not like it’s giving any actionable intelligence. You’re at your first version. I know in a year from now, it’s gonna be a highly advanced AI robot that’s gonna tell me all these great things, but it’s not now.
So I, I think you need to step back and rethink your entire plan here. I mean, I think you got a gestalt of something, but you guys are so out of the ballpark on what you should be asking for or what you should be doing.
Ramya: So I - we should be at - first of all, thank you for that. We, we actually do appreciate the advice and we’d love any other feedback or advice that you guys have.
The demo that we showed you is a very pared back version of what we’re actually putting in our beta launch. In our beta launch, you can actually take a deep dive into each of these companies, see the industries that they play in, see trends over time for these four categories and see a lot more information. And it actually does have actionable intelligence. We just - with our dev version, you know, we’re always a little nervous about showing a dev version just cos there’s so, you know, we’re still in development. But we, we do understand, you know, where you’re coming from. And I think for us we’re just starting out on our journey of fundraising for the seed.
Michael: How interested would you be at raising a million bucks at like 6 million?
Ramya: So we actually have raised a family and friends round which is -
Jillian: That was one of the questions.
Ramya: Yes. So we actually ended up, uh, giving shares out for the family and friends round at a 4 million valuation.
Michael: And when did you do that?
Ramya: Uh two months ago?
Rachel: September?
Michael: So five minutes ago -
Ramya: Yeah.
Michael: - your company was worth 4 million bucks. And you - and now what’s the $26 million difference?
Ramya: So I, what we’re actually - one, we think that we’d like to close the seed round around January or February, after we’ve actually signed a contract with the company that we’re going to be launching with. And we’ll have, by then, we hope to have at least three other major, um, household names as beta users that are on the road to getting signed licenses and contracts. And then at that point, we think, the valuation is more worth it. Right now, I totally agree. We’re pre-revenue and we haven’t launched a beta, but –
Charles: I wanted to jump in here. I mean, we do a lot of enterprise software investing at my firm, and the bigger the ticket, the more important I think it is to have somebody early on who understands the go to market.
Ramya: Mm-hmm. Mm-hmm.
Charles: And then when you go to market, it’s a couple things. It’s understanding the price. Sort of the ‘why’ of the price. And I’m, I’m struggling to understand why 500k is the right price for this product, who buys it and why. And personally, I’ve just found when you have a wide valuation gap between expectations on both sides, I personally have never been successful at closing gaps that are bigger than about 50%. It just, it requires too much movement from one party probably to a place where either I’d be uncomfortable or you’d be uncomfortable. So for me, this one’s a pass and um, I, it’s - I’m struggling cos I feel like there’s a nugget of an idea here and it just didn’t land for me.
Ramya: Okay.
Charles: But -
Ramya: Sure. And to, if it can help to clarify in the pricing, so what we’ve heard on the, the enterprise SaaS side, you need to show - if you can save more than 3x from what the current process is then your pricing is reasonable, right? Like if it’s - is that, is that not good -
Michael: No, I know your, your, your, your sale price is com - is wrong. Your valuation price is wrong. Your expectations on timeline is wrong. Like I’ve, I’ve sold over a thousand large companies. I have over a hundred sales reps. I mean, I’ve been in this land my entire career. I mean, you’re getting some really bad advice. And you’re - it’s like you’ve gone to a grocery store, starving and just, you know, going like crazy there. Like your numbers just don’t make any sense. And the thing is, what I don’t like about this is that - I so agree with Charles, like, I like you two actually, and I like what you’re doing, and as a nugget, and if you just had a reasonable valuation and a reasonable expectation, I gotta tell you, I think I would invest in this. So, for me I’m gonna pass, but I’m annoyed because I kind of wanted to invest, but I just, it’s so far off the mark for me.
Ramya: And do you mind if I ask you, what do you think is a reasonable valuation right now?
Michael: 6 million.
Ramya: Okay.
Michael: Best.
Ramya: Okay.
Phil: So I really believe that the two of you have identified an area that you believe is a real need in the market because you’ve lived it. But the issue I have is that I don’t think you have the team. There’s no sales team yet in place. And I have seen similar products that are providing the same sort of solution. But then, you know, as we’ve all mentioned, the showstopper for me is that valuation. Knowing where you are today and hearing 30 million it - that’s a showstopper. So I’m going to pass.
Ramya: Well, again, thank you for the feedback. We appreciate it.
Sarah: So from my perspective, I mean I love seeing two female founders who are technical. I mean, that’s badass. Like more power to you. The fact that you’re lawyers who are not doing that anymore - I’m a lawyer who’s not doing it anymore. Congratulations. You think that you made -
Phil: You made it out.
Sarah: You made the right choice. Um, so I love that. I love that you’re super confident. You know, I think, I’m not gonna harp on valuation cos everybody’s done that.
And the other thing is you struck me as a little bit cagey around answers to basic questions that investors are gonna need. You know, like sometimes we get pitches from people who say, please sign this NDA before you look at this deck. I think the reality is we see this stuff all the time. You should be able to communicate the basic things that we’re gonna need to know to make this decision. So for all those reasons, it’s a pass for me.
Jillian: You are - the two of you are so sharp. You have accomplished so much. Okay. It is clear that you’re the type of people that we wanna invest in. And, by the way, you’re absolutely right: to find two women engineers, it’s like, you know, just fantastic. Now, I think you’re realizing that you cannot do this at the 30 million. It’s not that you can’t; it’s that you shouldn’t. Because you’re really going to want to create a trust and a relationship with the first investors in this. Okay. And you’re wanting to say, this is a win-win. We’re excited. We want you to be as excited as we are. Okay. It’s very interesting that you did a $4 million valuation. Why not just fill up that round at like a four or five? Okay. And let us all have a little toehold. Let’s let us have a little step in.
Ramya: If we’re willing to do that now, are you guys invested to say, come help us fill out that round?
Jillian: At a five?
Ramya: At a five? Yes. Would, would any of you reconsider it at that kind of valuation?
Phil: Well, coming off a $30 million valuation seems like such a great deal, you know? Wow.
Michael: Was that your tactic?
Phil: That was a good set up.
Michael: Is that your tactic? Cut your valuation 90%.
Phil: You set us up great. That was nice.
Michael: That was a brilliant pitch.
Phil: Today only, 85% off.
Ramya: Actually, that’s true. Today only.
Michael: I’ll take two.
Ramya: No, but you know, we are open to feedback. We hear what you guys say. We know right now we aren’t worth 30 million. We’re looking at, once we have ideally a multi-year contract, three or four major companies in the pipeline, maybe, maybe we are, maybe we’re not then, but at least it’s a starting point for negotiation. But today, coming to talk to you guys, you’re a hundred percent right and we take that feedback.
The investors kind of laugh about the valuation fire sale, but no one takes the bait and goes in.
Rachel: Thank you. Thank you. Thank you all.
Jillian: Okay.
Michael: Well that was some really bad advice they got from other people.
Phil: Yeah.
Sarah: It’s like, do you see this -
Michael: You could get that valuation if you were a multi repeat entrepreneur and you had this crazy good track record. And they’re just - not even buying into your company, just the person.
Phil: There aren’t a lot of cases where you would pay that.
Sarah: When they said that, there was a collective like - time stopped in this room and it was like matrix bullet timing. And we were like whaaaaat?
Before the investors start choosing which pill they’re gonna take from Morpheus, I stepped in the room to bring things back to reality.
Josh: So my question about the 30 million is like, is it less about the number or is it more about what it actually signals when someone comes in here?
Sarah: Signal.
Michael: Signal.
Phil: Both. It’s both.
Sarah: It’s just poor judgment. It’s like kind of a stinginess almost, because if you’re trying to preserve that much for yourself, like the VP of Sales hire and all these other hires they have to make, how are they gonna deal with giving away equity? And then it just shows like they’re in a bubble of complete lack of reality around what is reasonable.
Charles: If you’re gonna come in with a 30 million number, you should expect, I’m gonna get push back on this. You should be like, prepared to say like, look, I know 30 -
Phil: You better have a kick ass app.
Charles: Or just a really strong story.
Michael: Maybe they were like, we’ll go for 30, we’ll settle at 25.
Josh: But I mean, does the founder even need to be - at that stage, it doesn’t have a lead. Like they have their past valuation, which they know is actually a matter of fact, but this next valuation, it’s not actually real. Like what? I mean, do they even need to bring that up?
Michael: Look, at the end of the day, it’s what it signals, right? And remember something, everybody should realize something when they go pitch investors is that they’re competing against our money, against all the other investments we hear about, and sometimes you just don’t have time to go fix everything and fix the 16 problems that they have. I want someone to come on in here with a reasonable valuation and a reasonable road and a reasonable, you know, trajectory for my exit.
Josh: But if they don’t have a lead, they don’t even have a valuation.
Jillian: So here’s the other, so here’s the other big issue. I’m worrying where they’re getting their advice. Right? Because if I can’t be there and they’re in DC, okay, and they kept saying, we’ve talked to many people, I’m thinking to myself, who the heck are they talking? Who are those many people they’re talking to? And how many other, you know, nuggets of quote unquote advice -
Josh: What other bad advice have they heard.
Jillian: - that is, you know, that is coming down the pike?
Phil: Anytime the answer to the question of where that valuation comes from is: people told us to price it at that amount. When those people aren’t investing, anytime you hear that, that’s a no. I mean, it’s like the valuation’s gotta come from the market.
Sarah: It’s an art, not a science, but you still have to have facts or patterns or things to point to in the market. Analogy, it’s not -
Phil: You can’t pluck it outta thin air.
Jillian: No.
Josh: So then when the founder finally in the end said, alright, I wanna offer you, I’m gonna open up the rest of this, uh, friends and family round for you guys to fill up -
Phil: For two minutes only. Buy now. I mean, what does that tell you?
Josh: I mean, it sounded like they were serious. Jillian, you were -
Phil: They were serious. But what does that tell you?
Josh: The rest of you didn’t take that seriously at all.
Phil: Well, that’s another -
Josh: Charles, you’re shaking your head.
Phil: I would rather that they stand there and have conviction and reasons behind a $30 million valuation than drop their drawers and go from 30 million to 5 million.
Jillian: I disagree with you adamantly about that. What is wrong with all of you? They’ve been obviously getting such bad advice.
Phil: And they’re taking that advice.
Jillian: No. But then they came to an aha moment. Now, I think that it was wrong for them to say, this is, oh, you know, at one time she said, it’s only for today. What she should have said is, let’s build this out. Okay. Can I educate you a bit more about the product? Okay. Then let’s talk about the valuation. I don’t think it should be four or five or six or whatever it is, but I realize we made a mistake. Okay. And we all clearly need more, we need to learn more about this.
Phil: That would’ve been a better -
Jillian: That would’ve been a better approach.
Josh: Yeah. Well, those two, they’ll figure it out.
Jillian: Yeah, I’m hoping they do. I like them a lot.
About five months pass, and then we reached out to Ramya and Rachel to find out what they were up to and how things were going with BlueFoot. But after a few emails back and forth trying to arrange a time to talk, they went silent on us. Emails, text, phone, no response whatsoever. But by all appearances, including a few conversations we had with some outside investors, the company is still around.
So we decided to get back with one of our investors, Sarah Downey, to see if she had any insight into why what happened in the room was such a big deal. And actually Sarah says she thinks about that pitch pretty often.
Sarah: So they gave us t-shirts after that. And I remember, I love that t-shirt actually. It’s like super comfortable and I sleep in it all the time.
Josh: Really?
Sarah: Yeah. Yeah. So I think of them regularly as I’m sleeping in their branded t-shirt. And the thing I think about is how absurd that $30 million valuation was. Like, it was so absurd and so high. It was like - I was just completely struck by that. And so sometimes I sit, I’m in this t-shirt and I wonder what happened to them. Because that $30 million ask was so big and so crazy that I can see a world where they’re embarrassed by that. Because they’re, you know, they’re first-time founders. They were lawyers, so they weren’t really from the startup world. They’re in DC which can be a little bit insular around this stuff. Clearly, they were getting advice that was bad. Like, I don’t wanna be overly critical, because as a startup founder, you’re supposed to know everything and you go in knowing virtually nothing. There’s just so much you’re expected to do and be good at. But something as big as what do you value the company at is major. And, you know, it could be, it could be a classic case of this is embarrassing and we don’t wanna revisit this.
Josh: Yeah, that’s understandable, I guess.
Sarah: Yeah.
Josh: But what’s weird though, I mean, like I did hear from other investors that they did, they went ahead and lowered the valuation. So like, it sounds like they learned from it. And so I guess I wish they would just say like, yeah, we learned from it. We made a mistake, and like, we’re moving on. And here’s like, here’s where our expectations were and here’s where reality is, and like, we’ve adjusted.
Sarah: That would be awesome. That would be awesome. Because it’s like one of the things that we look for as investors is a grittiness and a willingness to learn. Because you will not have all the answers, therefore, what happens when you get it wrong? Can you quickly get back on your feet? That’s what we care about more than do you have the right answer to begin with? And actually, if I recall correctly, we ended that pitch with them and they said, oh, you know what? Sorry, we were way off. How about like 4 million? Was it four?
Josh: I think it was six. Actually, it was five.
Sarah: It was like, oh geez. Like, what just caused such a cliff of value in five minutes? So coachability is good and learning is good. But I remember even in that pitch, going from 30 to six is such a big gap that you’re like, whoa, whoa, whoa. That doesn’t show good judgment either. Like what shows good judgment is: we marinated on this, we thought about it, we really took stock of what we’ve built. But just like be thoughtful about it and come up with something that you believe in.
Josh: Yeah.
Sarah: Because that 30 million felt like, hey, we talked to some people and they said this number, and here it is.
Josh: Yeah. So why, why is that a bad thing? Like, isn’t it a good thing for a founder if they can own more of the company? Doesn’t that mean they’re more incentivized to grow the company?
Sarah: Well, it can be bad in a couple ways because if you come outta the gate saying, this thing is worth $30 million, then you have to create value to increase that over the next 12 to 18 months when you go out and fundraise again.
Josh: Oh, so like on the next round, like it has to be higher or you’re gonna run into problems.
Sarah: Yeah.
Josh: You can’t just raise again at 30 million a year from now.
Sarah: No. But by putting it super high, it also makes it difficult for investors to get a significant chunk where we are invested mentally. You know, like if I was gonna put 2 million bucks on a $30 million valuation, like I’m not getting a significant ownership piece of that. So yeah, you want the founders to have enough ownership where they feel motivated and committed to this, but at the same time, the investors need that too. And so like this is a pre-seed level company in terms of number of people and product development, and yet they’re asking for seed or more valuations. Like there’s series A companies that have those, that valuations. It’s just not in alignment at all.
Josh: So like what do we learn from all this? Like what can we take away?
Sarah: Oh man. I guess that I, you know, we want you to win. Like, everybody’s rooting for you. You know, it’s not that people are against you. I think you have - a really good investor is a partner. They’re not an enemy. It’s a relationship where both parties win if the company does well. And when things are going badly in a company is often the time when you need to be the most transparent, because we’re here to help you through that. We’ve seen a lot of companies, we have pattern matching around crises, frankly, and if you just come in and you’re like, hey, nope, arm’s length, everything’s good, you know, and you don’t trust us to help you in those situations, it’s just not a good relationship. And it doesn’t do anybody a service, including the company. And again, we’re both here to see this thing win.
We did talk off the record to an outside investor who decided not to go in on BlueFoot, and they told us that Ramya and Rachel did end up lowering the valuation. We also heard that BlueFoot has signed on a couple customers, but we weren’t able to confirm any of that. And while it’s disappointing that the founders wouldn’t talk to us, I still think there’s a lot to learn from this pitch. Because it’s true that valuation isn’t a science, and maybe in this case, one piece of bad advice torpedoed the whole pitch. And like Sarah said, as a founder, you’re expected to know all this stuff, but sometimes the only way to figure it out is to make a mistake. Or you listen to the podcast about somebody else making that mistake.
Our show is hosted by me, Josh Muccio, produced by Heather Rogers, Kareem Maddox and Molly Donahue. We’re edited by Blythe Terrell. Theme music by The Muse Maker. Original compositions from Breakmaster Cylinder and The Muse Maker were mixed by Enoch Kim. Lisa Muccio planned the recording of this pitch. And our disclaimer: no offer to invest is being made to or solicited from the listening audience on today’s show.
You can listen to more episodes of the pitch for free on Spotify or wherever you listen. We’ll be back with a new episode next Wednesday.
The Founders
BlueFoot
Ramya Possett is the co-founder of BlueFoot, a competitive-intelligence tool that helps large companies track their competition, which pitched on The Pitch. Possett co-founded BlueFoot with Rachel Lee. BlueFoot pitched to investors Jillian Manus, Charles Hudson, Phil Nadel, Michael Hyatt, and Sarah Downey on The Pitch.
BlueFoot
Rachel Lee is the co-founder of BlueFoot, a competitive-intelligence tool that helps massive companies track their competition. She built BlueFoot with co-founder Ramya Possett, and the two pitched the company to investors on The Pitch.